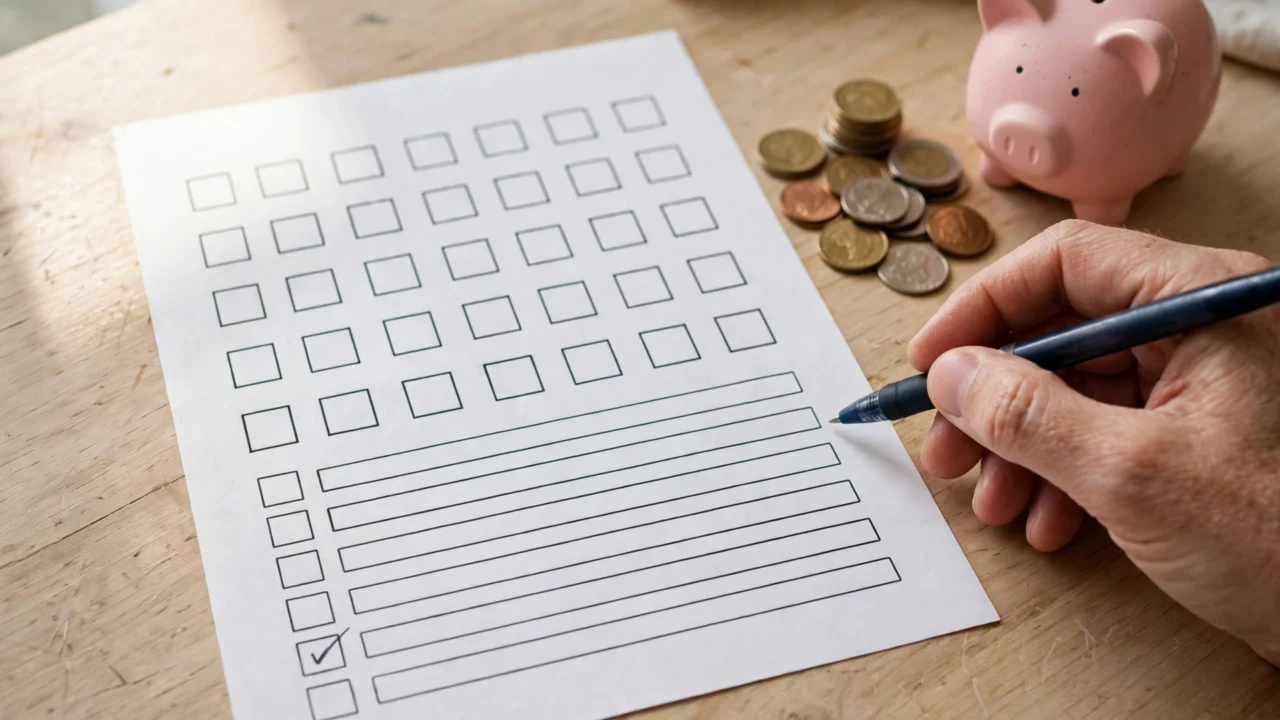
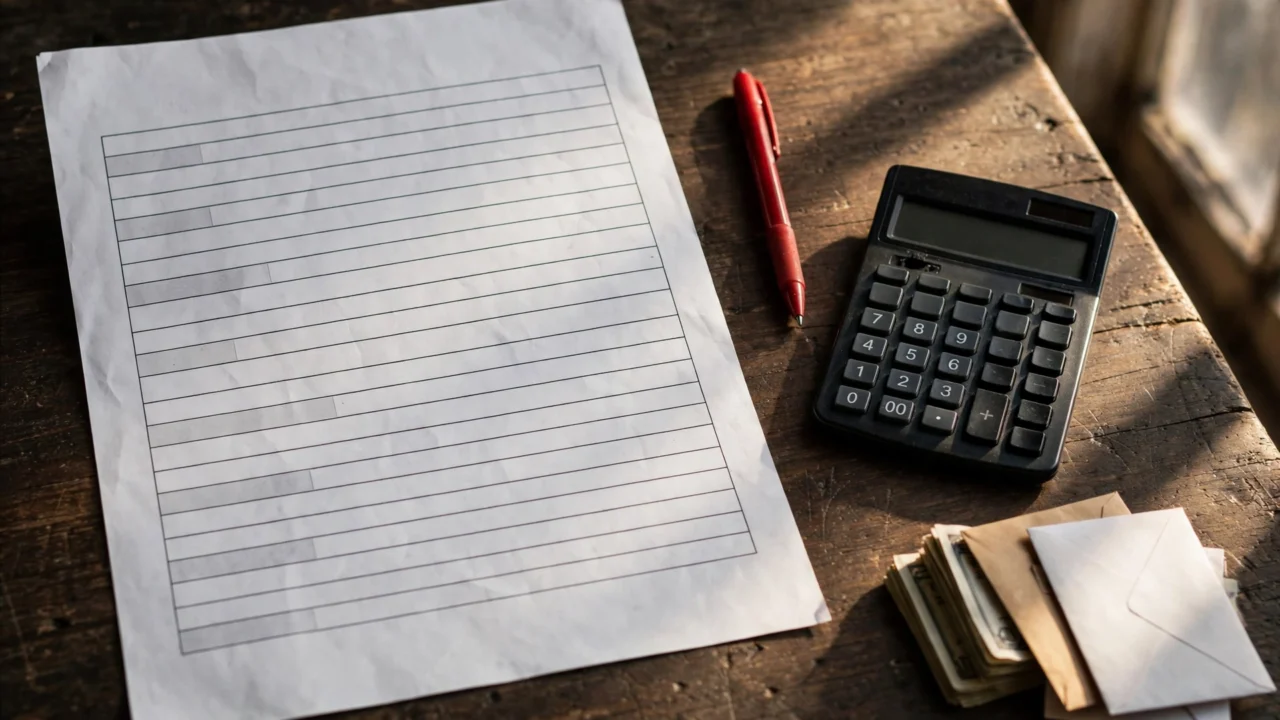

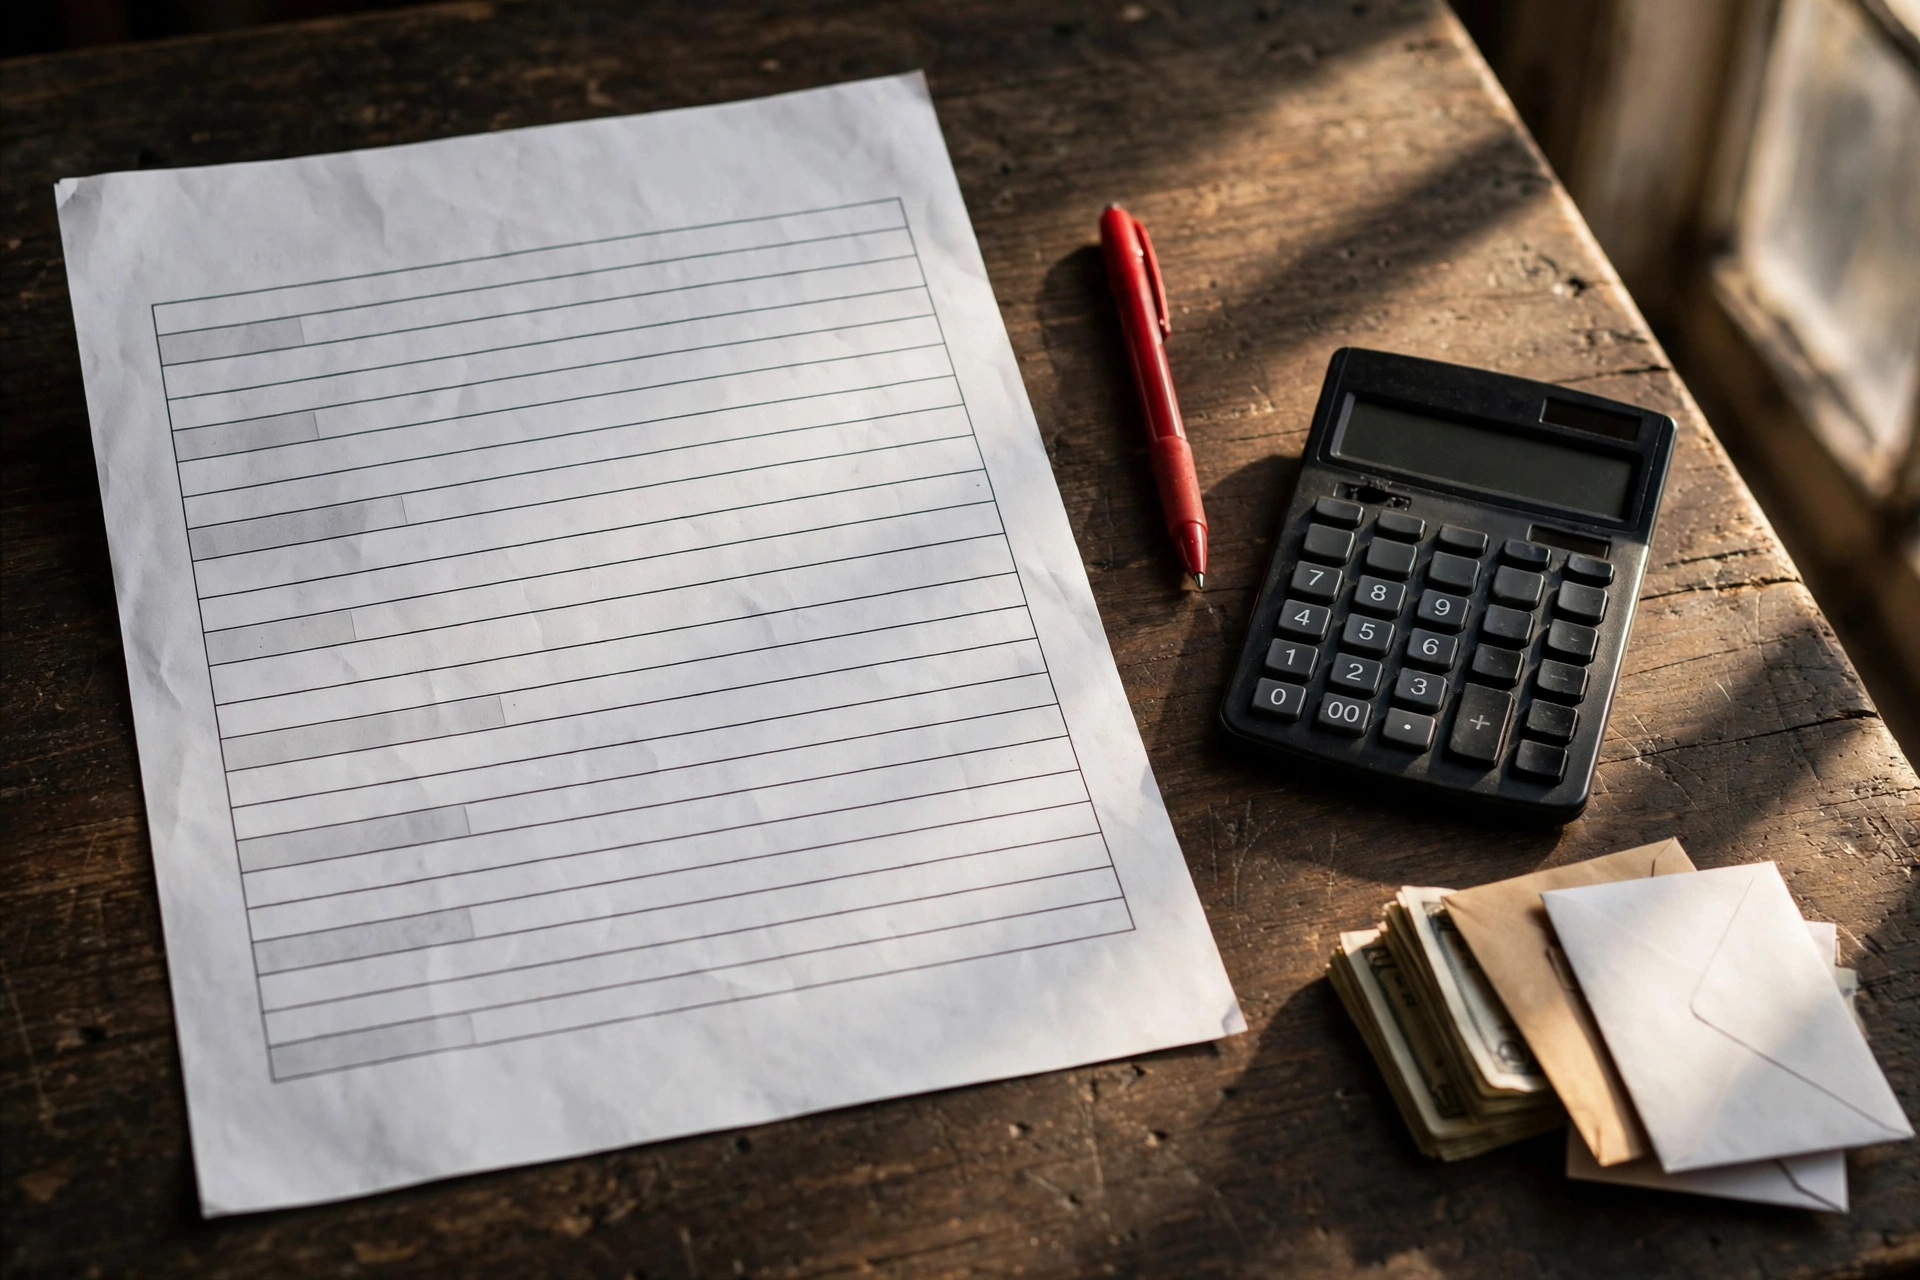
A debt tracker printable is a single worksheet where you list every debt — the balance, the interest rate, the minimum payment — and update it by hand each month as balances fall. It is deliberately low-tech, and that is the point: debt shrinks fastest when you confront it regularly, and a printed page on your desk is much harder to ignore than a banking app you never open.
How a debt tracker printable works
The worksheet has one row per debt and columns for the details that matter: creditor name, total balance, interest rate, minimum monthly payment, and the extra payment you are making. Each month you write in the new balance. Watching the numbers drop — especially on the debt you are attacking first — creates momentum that minimum payments alone never provide.
There is a second, quieter benefit. Most people in debt do not actually know their total. They know roughly, which means they know optimistically. Writing every balance on one page replaces vague anxiety with a concrete number and a concrete plan. That clarity is the moment a debt payoff journey really begins.
What to include on your tracker
- Creditor and debt name — “Store card”, “Car loan”, “Overdraft”. Plain labels, no judgement.
- Current balance — the full amount owed today, not the credit limit.
- Interest rate (APR) — this determines which debts cost you most.
- Minimum payment — what you must pay to stay current.
- Extra payment target — the additional amount going to your focus debt.
- Target payoff date — an estimate that updates as you go.
- Monthly update boxes — a row of small boxes, one per month, where you write the shrinking balance. This is the satisfying part.
Snowball vs avalanche: pick your payoff order
Your tracker needs a strategy — which debt gets the extra payments first. The two classic methods:
The snowball method
Attack the smallest balance first, regardless of interest rate. You get a fully-paid-off debt quickly, and that win fuels the next one. When the smallest is gone, its payment rolls into attacking the next smallest. Best for motivation.
The avalanche method
Attack the highest interest rate first. This saves the most money in interest over time, though the first win may take longer to arrive. Best for minimising total cost.
Either method works; the one you will actually follow is the right one. Mark your chosen order clearly on the tracker — a numbered column showing payoff priority keeps the plan visible every time you update the sheet. And while you are paying debt down, keep new borrowing off the table: our guide on avoiding common debt traps explains the habits that undo payoff progress.
Using the tracker month by month
- Fill it in completely once. Gather statements, log into accounts, and get every balance and rate accurate. This is the hardest step — after this, it is maintenance.
- Set the extra payment. Decide one fixed additional amount you will pay toward the focus debt each month, and automate it if possible.
- Update on the same day monthly. Pick a date — the 1st, payday, whatever sticks — and write in every new balance. Colour, tick, or highlight the focus debt’s progress.
- Celebrate paid-off debts. Cross the whole row out with a thick marker. It is a genuine achievement; mark it like one.
- Roll payments forward. When a debt clears, its entire payment (minimum plus extra) moves to the next debt on the list. Your total monthly debt payment stays the same while its impact grows.
- Re-check rates yearly. If a balance transfer or consolidation could cut your interest meaningfully, it is worth considering — see our guide to consolidating credit card debt for how to evaluate the options.
Keeping your credit healthy while you pay down
Paying down debt steadily is one of the best things you can do for your credit score — on-time payments and falling balances both help over time. If you want to understand the mechanics, our explainer on what a credit score is and how to improve it covers the habits that matter. Just remember: closing old cards the moment they are paid off is not always wise, as it can shorten your credit history.
When the numbers feel overwhelming
If the total on your tracker makes your stomach drop, that is normal — and it is exactly why the tracker exists. A plan you can see beats worry you cannot measure. Work the plan one month at a time: minimums on everything, extra on the focus debt, update the sheet, repeat.
And if debts are genuinely unmanageable — you cannot cover minimums, or you are borrowing to pay borrowing — free, independent debt advice is the right next step, not another month of minimum payments. In the US, the Consumer Financial Protection Bureau’s Ask CFPB resource answers common debt questions in plain language and points to reputable help.
The bottom line
A debt tracker printable turns an abstract burden into a visible, shrinking list. List every debt honestly, choose snowball or avalanche, automate one extra payment, and update the sheet monthly. The balances will fall — slowly at first, then faster as payments roll forward. Print the sheet this week; future you will be glad you did.
This article is for general information only and is not financial advice. If you are struggling with debt, consider speaking to a qualified adviser or a free debt advice service.